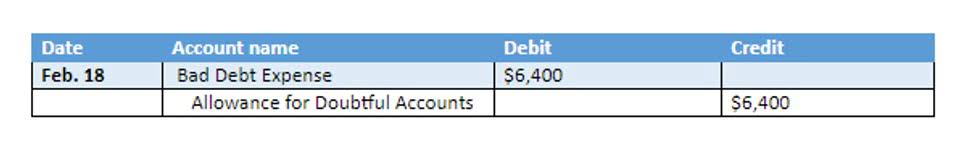
It is a tradition design and used to post debit amount using prefix “To” with particulars and post credit amount using prefix “By” with particulars. We might do this by using the services of a reputable credit agency such as Experian. As with most commercial entities, credit agencies charge for their services. For the past 52 years, Harold Averkamp (CPA, MBA) hasworked as an accounting supervisor, manager, consultant, university instructor, and innovator in teaching accounting online.
The Role of Accounts in Financial Reporting
This could be cash, inventory, rent, sales, or any other item a business deal with. Whether you’re running a small shop or managing a large company, accounts are at the heart of good financial management. In addition, financial statements disclose details concerning economic resources and the claims to those resources. An account is a part of the accounting system used to classify and summarize the increases, decreases, and balances of each asset, liability, stockholders’ equity item, dividend, revenue, and expense.
- Since both nationalised and privatised banks are registered with the Reserve Bank of India, they are the safest places to store your money.
- In this section, we’ll briefly review the roles of accountants vs. CPAs and tax professionals.
- A savings account also comes with an ATM card or a debit card, which allows you to withdraw cash or make digital transactions at different points of sale.
- Examples of typical financial accounts are accounts receivable (money a company is owed), accounts payable (money a company owes), sales, loans, and mortgages.
- We’ll come back to this topic later, but for now, just know that an account is a category that we use for tracking and reporting.
- The hallmark of neutrality is its demand that accounting information not be selected to benefit one class of users to the neglect of others.
We and our partners process data to provide:

Some of these accounts even offer the facility to maintain a zero balance without penalties. This makes them one of the best accounts to keep your money safely while maintaining liquidity. An account may seem like a small part of inheritance taxes accounting, but it plays a huge role.
Using Accounting Software
These are measured form period to period and are closed at the end of the period so as not to be mixed with the next period’s records. Assets, liabilities and equity do not perform closing procedures like revenue and expense accounts. By understanding the principles of accounts and leveraging modern accounting tools, businesses can streamline their financial processes, make informed decisions, and achieve long-term success. As accounting continues to evolve, the importance of well-maintained accounts will remain a cornerstone of effective financial management. In accounting, accounts are categorized as either temporary or permanent. Temporary accounts, including revenues and expenses, are closed at the end of each accounting period to reset balances for the new period.
This ensures that the increase in one asset is offset by a corresponding decrease in another, keeping the accounting equation balanced. Liabilities represent the debt obligations that the company owes to creditors. Liability accounts have a credit balance and appear below assets on the balance sheet.
Temporary accounts are accounts that are closed, zeroed out and reset at the end of an accounting period. These tools not only enhance efficiency but also provide businesses with real-time financial insights, enabling faster and more informed decision-making. With an online savings account, you never need to physically visit the bank. You can check your account balance, pay bills, and transfer funds digitally through the bank’s mobile application. If you’re already running a business, make sure your accounts are kept up-to-date and reviewed regularly. Clear, well-organized accounts are the key to a financially healthy and successful business.
Why Choose a Savings Account?
Assets are resources that the company can use to generate revenues in current and future years. Asset accounts have a debit balance and are always presented on the balance sheet first. When opening a bank account, you get to choose the type of account. Depending on your needs, you can choose either a savings or a current account. While the former is suitable for everyone, the latter is better for working professionals and business owners. Before deciding on which bank to open an account with, you can review the interest rates offered on savings accounts, account opening charges, and minimum balance requirements.
This focuses on the use and interpretation of financial information to make sound business decisions. It’s similar to financial accounting, but this time, it’s reserved for internal use, and financial statements are made more frequently to evaluate and interpret financial performance. In accounting and bookkeeping, accounts are chronological records of changes in the value of a company’s liabilities and assets.
One of the biggest benefits of these accounts is that the bank pays you interest as a percentage of your account balance. So the more money you keep in this account, the more interest you earn either quarterly, half-yearly, or annually. All you have to do is select the correct account when entering a transaction, and the software updates everything automatically. To understand accounts better, let’s explore the different types that appear in accounting. Each one serves a different purpose and represents a different part of your business. With all the information in one place, accounts help you see the big picture.
This means that if you increase cash and then decrease cash, the account will show the net amount of all of these transactions. With advancements in technology, modern accounting systems have transformed how accounts are managed. Software platforms like QuickBooks, Xero, and SAP automate much of the recording, categorization, and reporting processes, reducing the manual effort required. Expense accounts, on the other hand, represent the resources used to generate income.
Classification of accounts
- For example, you can review your “Sales” account to see how much revenue you earned this month.
- Each version shows how much has increased or decreased over time.
- We might do this by using the services of a reputable credit agency such as Experian.
- As such, the Knights Templar are sometimes credited with creating the foundations of today’s banking system.
He is the sole author of all the materials on AccountingCoach.com. For the past 52 years, Harold Averkamp (CPA, MBA) has worked as an accounting supervisor, manager, consultant, university instructor, and innovator in teaching accounting online.
This list includes all the accounts used in the business and helps keep everything organized. Businesses must provide financial reports to government agencies, banks, or investors. These reports are built using the information recorded in your accounts. If your accounts are incomplete or inaccurate, your reports will be unreliable and that could lead to fines or missed opportunities. An account is like a folder that holds all the activity for one specific item.
What does this question mean ‘Do you want to see your account statement? ’ The ATM or online account service is asking whether you want to see a list of your recent transactions. Similarly, an Inventory ledger can track the cost and quantity of goods in stock, enabling businesses to optimize inventory levels and reduce carrying costs. This approach provides a built-in error-checking mechanism, reducing the likelihood of discrepancies and ensuring accurate financial reporting. Once your bank account has been activated, you need to start with an initial deposit. The amount varies from bank to bank and also depends on the account type.
Also known as permanent accounts, real accounts include asset, liability, and capital accounts. They are not closed at the end of every accounting period, hence are measured cumulatively. In Accounting, an account is a record of all relevant business transactions in terms of money. Account consists all the statements by data wise regarding the business transactions as person, companies, representatives, asset & liabilities, income & expenditures, profit & loss . These entries, often called postings, become part of a book of final entry or ledger. Examples of typical financial accounts are accounts receivable (money a company is owed), accounts payable (money a company owes), sales, loans, and mortgages.