
This account then calculates the net income or net loss for the period. Calculating net income or loss requires the utilization of the income summary account to compile the financial impact of revenue and expenses for a specific period. The closing process involves the journal entries to close revenue and expense accounts normal balance as part of the regular accounting cycle. The purpose of an Income Summary Account is to accumulate the balances of revenue and expense accounts and facilitate the transfer of profit or loss to the retained earnings account. By the end of this article, readers will have a firm grasp on the mechanics and importance of the income summary account, empowering them to navigate the world of financial reporting with confidence and clarity. As you can see, the income and expense accounts are transferred to the income summary account.
Accounting Crash Courses
- Similarly, when expenses such as salaries, utilities, and rent are incurred, they decrease the income summary account.
- Let us understand the advantages of passing income summary closing entries for an organization or an individual through the points below.
- Our solution has the ability to prepare and post journal entries, which will be automatically posted into the ERP, automating 70% of your account reconciliation process.
- An Income Summary Account, in accounting, is a temporary account used in the closing process to transfer the balances of revenue and expense accounts.
- Once the entries are finalized, the income summary closing entries are documented and transferred to the retained earnings of an organization or individual.
- Understanding the purpose and function of the Income Summary Account is essential for ensuring the accuracy and integrity of financial reporting.
We know that all revenue and expense accounts have been closed. If we had not used the Income Summary account, we would not have this figure to check, ensuring that we are on the right path. HighRadius offers a cloud-based Record to Report solution that helps accounting professionals streamline and automate the financial close process for businesses. We have helped accounting teams from around the globe with month-end closing, reconciliations, journal entry management, intercompany accounting, and financial reporting.
Company
An Income Summary Account, in accounting, is a temporary account used in the closing process to transfer the balances of revenue and expense accounts. After preparing the closing entries above, Service Revenue will now be zero. The expense accounts and withdrawal account will now also be zero. From this trial balance, as we learned in the prior section, you make your financial statements.
What are Some Examples of Transactions that Affect the Income Summary Account?
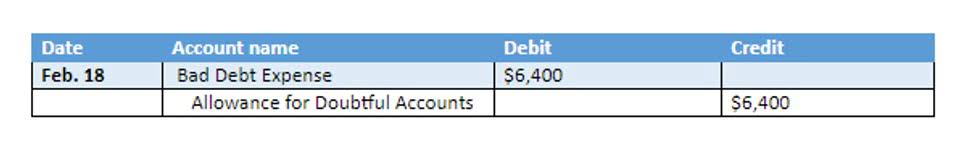
It serves as a temporary account, consolidating the company’s financial performance before the final step of closing entries. At the end of a period, all the income and expense accounts transfer their balances to the income summary account. The income summary account holds these balances until final closing entries are made. Then the income summary account is zeroed out and transfers its balance to the retained earnings (for income summary account corporations) or capital accounts (for partnerships). This transfers the income or loss from an income statement account to a balance sheet account. The income summary account is a temporary account into which all income statement revenue and expense accounts are transferred at the end of an accounting period.
What is Accounting?
While revenues and expenses in accounting records are reset to zero at the conclusion of a period, they are reported in the income statement to reflect profitability for the time. An income statement is a list of all revenue and expense accounts classified according to the type of revenue and expense. At the end of each accounting period, businesses prepare an income summary and an income statement. The first step involves transferring the balance of the income summary account to the retained earnings account through a journal entry. During the financial statement preparation, the Income Summary Account plays a crucial role in summarizing the net income or net loss for the period.
- The second is to update the balance in Retained Earnings to agree to the Statement of Retained Earnings.
- If this is the case, then this temporary dividends account needs to be closed at the end of the period to the capital account, Retained Earnings.
- Now that Paul’s books are completely closed for the year, he can prepare the post closing trial balance and reopen his books with reversing entries in the next steps of the accounting cycle.
- The debit to income summary should agree to total expenses on the Income Statement.
- It is a necessary instrument for the preparation of financial statements.
- It acts as a checkpoint and reduces errors in financial statement preparation by directly transferring the balance from revenue and spending accounts.
- Upgrading to a paid membership gives you access to our extensive collection of plug-and-play Templates designed to power your performance—as well as CFI’s full course catalog and accredited Certification Programs.
The purpose of the income summary account is to facilitate the process of closing temporary accounts and transfer their balances into the retained earnings account. The income summary account is a temporary account into which all income statement revenue and expense accounts are placed at the end of an accounting period. The net amount put into this account equals the business’s net profit or loss for the period. Shifting revenue out of the income statement, therefore, entails debiting the revenue account for the total amount of revenue recorded in the period and crediting the income summary account. The income summary account is prepared by debiting revenue accounts and crediting expense https://www.facebook.com/BooksTimeInc accounts.
- I imagine some of you are starting to wonder if there is an end to the types of journal entries in the accounting cycle!
- Additionally, it is important to note that the income summary account plays both roles of the debit and the credit at the same time when the company closes the income statement at the end of the period.
- Other accounting software, such as Oracle’s PeopleSoft™, post closing entries to a special accounting period that keeps them separate from all of the other entries.
- This process involves transferring the credit balance of the income and expense accounts to the income summary account, with the debit and credit sides then compared to ascertain the net income or net loss.
The Income Summary balance is ultimately closed to the capital account. Now for this step, we need to get the balance of the Income Summary account. In step 1, we credited it for $9,850 and debited it in step 2 for $8,790. Below are the T accounts with the journal entries already posted. We’ll use a company called MacroAuto that creates and installs specialized exhaust systems for race cars.
Leave a Reply